Salary progression (2014 to 2021)
📖 Note: This post is from the archives. It may reflect outdated views or a previous name. This blog post explores sensitive topics.
Money is a topic we often feel like we need to keep a secret. Asking your colleagues about their pay feels inappropriate and companies rarely share how much their c-levels make. I feel very strongly about the importance of sharing salaries as someone who is part of an underserved community.
I didn’t get to have a normal childhood. I fled my parents’ and another relative’s abuse at 14 and moved in with my grandparents who, in turn, kicked me out for being trans. I had to drop out of school when I was 16 to start working. I had been building apps for several years and attended networking events often so finding work was hard but not impossible. As someone who was underage however (and had no access to trusted adults), I was constantly exploited. My early employment was often in some way under the table. The years leading up to my 18th birthday, I primarily worked on freelance contracts. It was high risk because I was using PayPal underage and had no recourse if someone didn’t pay.
This post may be heavy for some so here’s a TLDR if you’re only interested in the numbers:
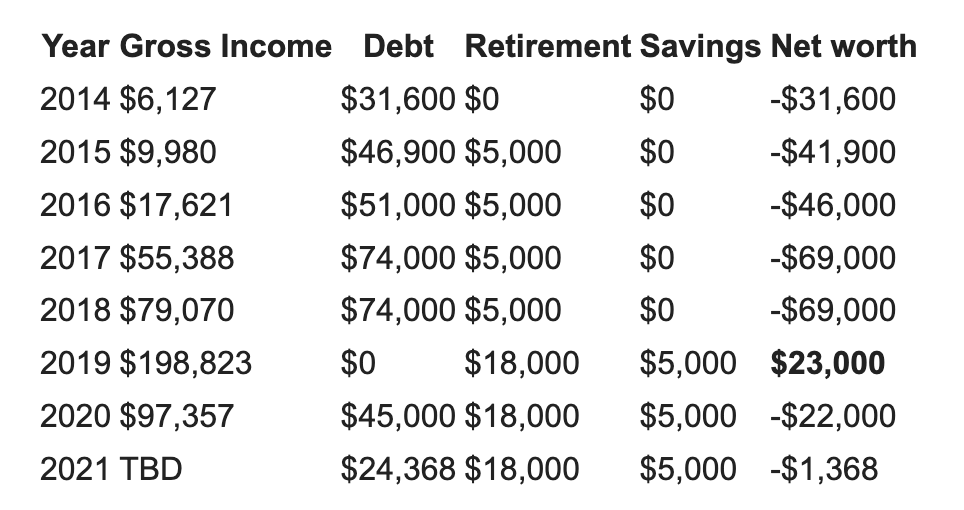
2014
In 2014, I made $6,127 according to my notice of assessment (I paid taxes on all my income because I was so scared of going to jail for tax evasion). This was less than $500/month and my rent alone was $1000/month. Looking back I could’ve lived in Coquitlam or Surrey but I lived in downtown Vancouver because it was faster to get to the office, which I often had to do on short notice. This was the start of my debt. Being at minimum $500 in the hole every month added up quickly. It also didn’t help that I have so much trauma around food that required me to eat out for almost every meal. Because Vancouver is Vancouver, I was spending more in a day than I made in a week on food.
2015
In 2015 I was paid $9,980. This was much better with over $300 more per month but still nowhere near enough to cover my expensive traumatized lifestyle. Miraculously I was able to put away $5,000 in my RRSP (which for those who don’t know is a registered retirement account from the Canadian government). Honestly, this probably just increased my debt but I am glad I did it because it meant I had +5K in net worth that I couldn’t touch.
2016
When I turned 18 in 2016, I was able to make $17,621. This was because I was able to become a legal full-time employee with proper paycheques and benefits. This basically eliminated how often I was exploited since I could finally have a verified PayPal account.
2017
I landed my first good tech position at Realm in 2017. This significantly increased my income and I was no longer in the red every month. I moved apartments to something more reasonable since Realm was remote and this started my journey of recovery.
2018
I didn’t increase my debt at all during the rest of that year and into 2018. I was living within my means and it was great but one thing that was still soul crushing was my debt payments. At this time I didn’t know the power of consolidation loans so I was paying around $2,000/month on minimum payments for cards with 21% ARRs.
2019
In 2019, the company I worked for, Travis CI, was acquired by an investment firm and everyone got a hefty bonus. This bonus almost entirely went to debt but allowed me to also save some money putting an additional $13,000 into my retirement fund and $5,000 into a regular savings account.
2020
I was finally out of debt. A reset button. But unfortunately this bonus didn’t change my bad habits or erase the mountain of trauma. When coronavirus hit, I purchased a lot of things because I was bored and stuck at home but I also went overboard on helping people. I was the first to offer my credit card up when one of my acquaintances needed help and would contribute to stranger’s GoFundMe fundraisers. But instead of donating $25, $50 or $100, I felt obligated to meet their goal. I was frequently donating $1,000 here and $2,500 there which sure, made the person’s day, but I could not afford it and it was a primarily a means for a dopamine hit because life was so grim. This behaviour got me into debt again. $45,000 and honestly I hated myself for it. After hitting rock bottom and wanting a change, I hired a financial advisor to help me get my shit together. In the past eight months, I have dropped my most recent debt load from $45k to $24,368.
2021
In these past eight years I’ve learned two things with regards to trauma and my path to financial independence. 1. Put your own oxygen mask on first! and 2. It wasn’t my fault but it is my responsibility. The first point is something that was hard for me to swallow. I love helping people. Meeting someone’s fundraising goal for top surgery or giving a homeless man a $20 bill. I like making people’s day. But I need to be on the path of financial independence first and help people second. If I want to meet my goals of adopting a long-haired dachshund or buying a farm so I can get chickens, I need to put myself first and help others only once I genuinely have the money to do so. This lesson felt really egocentric and selfish at first but with help from my therapist and financial advisors, I’ve started to internalize this. I am worthy of fulfilling my dreams.
At one time I would have argued that it was my fault that I experienced abuse. It never was. Although I still struggle with this self-blame, through therapy and better relationships, I’m finally able to move on. While it wasn’t my fault, it is still my responsibility to deal with the mental health struggles. If I didn’t put in the effort to improve, I have no idea who I’d be.
This blog post was very heavy compared to my other ones. I hope that’s okay. If you are dealing with something similar, please know that you’re not alone and that you’re worthy of love.